A Complete Guide to First Time Buyer Benefits: Stamp Duty, ISAs and New Home Discounts
First time buyer benefits are government-backed tax reliefs, savings bonuses, price discounts and lender guarantees that cut the cost of buying a first home in the UK. As of October 2026, the main ones are Stamp Duty relief, the Lifetime ISA bonus, First Homes and Shared Ownership.
Key Takeaways
- England and Northern Ireland first-time buyers pay no Stamp Duty up to £300,000, and relief ends above £500,000.
- A Lifetime ISA adds a 25% bonus on up to £4,000 saved yearly for homes up to £450,000.
- First Homes gives 30% to 50% off new-builds in England, and every buyer must qualify.
What Are First Time Buyer Benefits Worth?
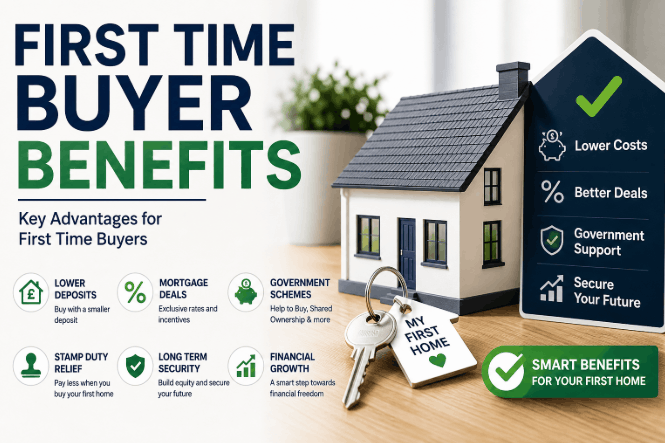
No single sum exists, because first time buyer benefits arrive as different kinds of help, not one payment. Stamp Duty relief saves up to £5,000, the Lifetime ISA bonus adds up to £1,000 a year, and a First Homes discount takes 30% to 50% off a new-build price.
No scheme in this guide pays a cash first-time home buyer government grant.
| Benefit | Type of help | Headline figure | Main limit |
|---|---|---|---|
| Stamp Duty relief | Tax relief | Nil tax to £300,000; saves up to £5,000 | England and Northern Ireland only; none above £500,000 |
| Lifetime ISA | Savings bonus | 25% bonus, up to £1,000 a year | Home of £450,000 or less; account open 12 months |
| First Homes | Price discount | 30% to 50% off market value | New-builds in England; income and price caps |
| Shared Ownership | Part-buy, part-rent | Buy a 10% to 75% share | Rent is paid on the remaining share |
| Mortgage Guarantee Scheme | Lender guarantee | Mortgages with a 5% deposit | Repayment mortgages only |
Who Counts as a First-Time Buyer?
A first-time buyer is someone who has never owned a residential property, in the UK or abroad. This includes inheriting even a partial share of a property, or being named on a commercial mortgage with a residential flat above it.
Which first time buyer benefits apply depends strictly on this status. If you have inherited or been gifted a property, ask your conveyancer, the licensed professional handling the legal side of your purchase – before assuming any benefit applies.
First Time Buyer Benefits and Stamp Duty: What the Relief Covers
First-time buyers in England and Northern Ireland pay no Stamp Duty Land Tax (SDLT), the tax charged on property purchases, on the first £300,000 of the price. HM Revenue & Customs (HMRC) charges 5% on the slice from £300,001 to £500,000, under rules in force since 1 April 2025.
The £500,000 limit works as a cliff, not a sliding scale. Stamp Duty relief for first-time buyers in England and Northern Ireland is all-or-nothing at £500,000.
A £500,000 purchase pays £10,000 with relief, while a £510,000 purchase pays £15,500 at standard rates. The maximum saving is £5,000, and every buyer on the purchase must be a first-time buyer.
The saving stays at a flat £5,000 for any price from £300,000 to £500,000, worked from the published bands. Below £300,000 the saving equals the full standard bill, so a £250,000 purchase saves £2,500.
First Time Buyer Benefits in Scotland and Wales: Why the Rules Differ
Stamp Duty benefits for first-time buyers differ by nation, because Scotland and Wales run their own property taxes.
MoneyHelper confirms that first-time buyers in Scotland pay no Land and Buildings Transaction Tax (LBTT), the Scottish equivalent of SDLT, up to £175,000. In Wales, first-time buyers pay the same Land Transaction Tax as everyone else.
| Nation | Property tax | First-time buyer relief | Nil-rate band (slice taxed at 0%) |
|---|---|---|---|
| England | SDLT | Yes | Up to £300,000 |
| Northern Ireland | SDLT | Yes | Up to £300,000 |
| Scotland | LBTT | Yes | Up to £175,000 |
| Wales | Land Transaction Tax | No | Up to £225,000, for all buyers |
Some lists present the Welsh £225,000 figure as a first-time buyer benefit. That is wrong: £225,000 is the standard Welsh band for every buyer.
Lifetime ISA: The 25% Bonus and the Planned Replacement
The Lifetime ISA (LISA) is a tax-free savings account in which the government adds a 25% bonus to up to £4,000 saved each year, worth up to £1,000 a year.
- Opening age: 18 to 39, with bonuses paid until age 50.
- Home price: £450,000 or less, in the UK.
- Account age: Open for at least 12 months before the purchase, with the clock starting at the first payment.
- Early withdrawal: Any other withdrawal before age 60 loses 25% of the total, so £5,000 returns £3,750.
- Help to Buy ISA: MoneyHelper states you can pay into the account until November 2029 and must claim the bonus by 1 December 2030, but only one of the two bonuses can go towards the same home.
HM Treasury published a consultation on 23 June 2026 proposing a First Time Buyer ISA, to be offered in place of the Lifetime ISA once available. At the time of writing, no launch date has been confirmed, so the current rules still apply.
However, those wanting penalty-free access to their savings in the interim might also consider using the best flexible cash ISA to build a deposit.
First Homes and Shared Ownership: Two Government Schemes for Buying Below Market Price
First Homes cuts the price of a new-build, while Shared Ownership cuts the share a buyer needs to purchase.
First Homes
gov.uk states that First Homes gives eligible first-time buyers in England a 30% to 50% discount on new-build homes, meaning you could see new homes discounted by £100k or more depending on the market value in your area. Household income must be under £80,000 (£90,000 in Greater London).
The price after the discount is capped at £250,000 (£420,000 in Greater London), and a council can set a lower cap.
Every buyer must be a first-time buyer, and the mortgage must cover at least half the discounted price. Councils can add local criteria for the first three months of sales. While the government doesn’t cap developer incentives, mortgage lenders typically restrict them to 5% of the property’s value.
Shared Ownership
Shared Ownership lets a buyer purchase a 10% to 75% share of a home and pay rent on the rest. The deposit is usually 5% to 10% of the share, not the full price, and a reservation fee of up to £500 applies. Staircasing, which means buying extra shares over time, lets owners increase their stake.
Low-Deposit Routes: The Mortgage Guarantee Scheme and Your First Home
The Mortgage Guarantee Scheme encourages lenders to offer 95% loan-to-value mortgages, meaning loans of up to 95% of a home’s price, by guaranteeing part of the lender’s risk. MoneyHelper lists 90% and 95% loan-to-value mortgages under the scheme, which became permanent in July 2025.
It excludes shared ownership, interest-only and guarantor mortgages, where a relative guarantees repayment. Deposit Unlock and track-record products, which can sometimes provide a pathway to a 100% mortgage in the UK, are lender products, not government schemes.
The government announced Your First Home on 26 September 2026, a new equity loan scheme for England to be confirmed at the October 2026 Budget. An equity loan is a government loan covering part of a home’s price.
The scheme is expected to pair a 2.5% deposit with a 20% equity loan on new-builds from participating developers, with an income cap and local price caps still to be set. It is not yet open, and the earlier Help to Buy equity loan closed to new applicants in 2022.
Do Both Partners Get First Time Buyer Benefits?
Couples face strict eligibility tests. HMRC guidance states that every buyer on the purchase must be a first-time buyer, and one non-qualifying buyer removes the relief entirely. gov.uk applies the same all-buyers rule to First Homes.
- Stamp Duty relief: all buyers must be first-time buyers, or standard rates apply to the full price.
- First Homes: all buyers must be first-time buyers and apply together, and their combined household income must stay under the cap.
- Lifetime ISA: each partner holds a separate account, and the £450,000 limit applies to the property, not to each account.
If one partner has owned a home before, you may still use the other partner’s Lifetime ISA, but the purchase loses Stamp Duty relief. Ask your conveyancer to cost both options before committing.
Where sources disagree: some conveyancing guides say every co-buyer must be a first-time buyer for a Lifetime ISA to work. gov.uk’s conveyancer guidance lets a Lifetime ISA holder buy jointly with someone who is not a first-time buyer, and the gov.uk position takes precedence.
How to Claim Each Benefit: Documents and Where to Apply
Confirm eligibility using the couples rules above before starting any step below.
- Stamp Duty relief: Give your conveyancer your first-time buyer details, and they claim the relief on the SDLT return. No separate application exists.
- Lifetime ISA: Open the account with an ISA provider at least 12 months before buying. At purchase, you sign a first-time buyer declaration, and the provider releases the funds through your conveyancer.
- First Homes: Apply through the developer or estate agent selling the home. The council checks eligibility, so have your previous tax year’s income evidence and your conveyancer’s details ready.
- Shared Ownership: Contact a Shared Ownership provider and pay the reservation fee, up to £500.
- Mortgage: Lenders typically ask for photo ID, proof of income and bank statements, and exact lists vary by lender.
Each government scheme for first-time buyers runs through a developer, provider, council or conveyancer.
What to Do If a First Time Buyer Benefit Is Refused
The route used in the steps above decides who to contact.
- Lifetime ISA: Complain to the ISA provider first, then take an unresolved complaint to the Financial Ombudsman Service, the body that resolves unresolved complaints about financial firms.
- Stamp Duty relief: Ask the solicitor who filed the SDLT return to amend it, since the relief is claimed on that return.
- First Homes: Contact the council that decided the case, because councils make First Homes eligibility decisions.
gov.uk does not describe a formal appeal process for First Homes decisions, so contacting the council is the closest available answer, not a guaranteed route to a reversal.
Can You Combine First Time Buyer Benefits?
Yes, many of these schemes are designed to work together, provided the property meets the individual criteria for each:
- Lifetime ISA + First Homes / Shared Ownership: You can use a LISA bonus to buy a First Homes or Shared Ownership property, as long as the final purchase price is £450,000 or less.
- Lifetime ISA + Stamp Duty Relief: These automatically combine. A £300,000 purchase would benefit from both the LISA bonus and a £0 Stamp Duty bill.
- Mortgage Guarantee + First Homes: The Mortgage Guarantee Scheme can be used on First Homes, but it explicitly excludes Shared Ownership properties.
The Bottom Line on First Time Buyer Benefits
First time buyer benefits come as Stamp Duty relief of up to £5,000, a Lifetime ISA bonus of up to £1,000 a year, and First Homes discounts of 30% to 50%.
Wales has no first-time buyer Stamp Duty relief, and the planned Your First Home equity loan awaits the October 2026 Budget. Every buyer’s first-time status decides which benefits apply.
FAQs
Is there a government grant for first-time buyers?
None of these schemes pays a cash first-time home buyer government grant. Help comes as tax relief, a 25% savings bonus, price discounts, lender guarantees and, from the planned Your First Home scheme, an equity loan.
Is the Lifetime ISA being scrapped?
Not yet. HM Treasury consulted on a First Time Buyer ISA from 23 June 2026, to be offered in place of it once available, and no launch date has been confirmed.
Disclaimer: This article is for informational purposes only and does not constitute professional financial or legal advice; always consult a licensed conveyancer or financial advisor before making property decisions.